
Many people assume that once a creditor wins a court judgment, the debt follows them forever. In most states that isn’t true. Judgments have a shelf life. If the creditor doesn’t renew the judgment or take the other steps state law requires before the deadline, it can lose the right to garnish wages or freeze bank accounts.
A federal court has just made clear what happens when a collector ignores that deadline. On September 23, 2026, Judge Richard A. Jones of the U.S. District Court for the Western District of Washington ruled in Lucianna v. SB&C, Ltd. (No. 2:24-cv-00456) that two collection companies violated the Fair Debt Collection Practices Act (FDCPA) and Washington law when they garnished a consumer’s wages on a judgment that had already expired. The industry publication AccountsRecovery.net reported the ruling on October 5.
What happened
According to the court’s order, Debt Recovery Specialists, LLC won a $38,543.90 judgment against Darren and Janelle Lucianna in a Snohomish County district court on October 19, 2012. In 2018 it transcribed (transferred) that judgment to the county superior court. In March 2023 it assigned the judgment to SB&C, Ltd., also known as Skagit Bonded Collectors.
In January 2024, SB&C got a writ of garnishment against Mrs. Lucianna’s wages. The writ claimed the couple still owed more than $85,000, including more than $46,400 in interest.
The problem was that the judgment was no longer enforceable. Washington generally allows garnishment and other collection on a judgment for 10 years from its entry unless the creditor extends it. The collectors argued that transferring the judgment to superior court in 2018 started a new 10-year clock. The court had already rejected that argument in 2025. In its new ruling it held again that the judgment expired on October 19, 2022, more than a year before the garnishment.
What the court decided
- FDCPA violations. The court found that the January 2024 writ, by itself, was misleading about the “character, amount, or legal status” of the debt under 15 U.S.C. § 1692e. Collecting money the law no longer allowed also violated § 1692f’s ban on unfair collection practices.
- No “honest mistake” defense. The collectors said they sincerely believed the judgment would last until 2028. The FDCPA’s bona fide error defense is narrow, and the court rejected it here. The collectors’ own evidence showed they knew how to move to extend judgments and had done so in other cases. “Engaging in debt-collection litigation” didn’t count as a procedure designed to prevent the error.
- Labeled a consumer debt. The collectors argued the original loan was a business loan, which the FDCPA doesn’t cover. But their own garnishment papers called it a “consumer debt,” and they couldn’t prove otherwise.
- State-law violations, too. The court also found violations of the Washington Collection Agency Act and the Consumer Protection Act. It held that hiring a lawyer after receiving the garnishment writ was enough injury to support the claim.
- Emotional distress can go to trial. The court refused to rule out Mr. Lucianna’s emotional-distress damages. His testimony tied at least part of his anxiety to the garnishment.
The ruling decides liability only. Damages haven’t been set yet, and the defendants may still be able to appeal once the case ends. A trial-court decision binds only that case, but it’s a clear, well-reasoned example of how courts treat collection on a dead judgment.
Why it matters
Debt buyers often buy old judgments in bulk, sometimes for pennies on the dollar, and then try to collect years later. Interest keeps adding up on paper. In this case it more than doubled the balance. When a collector tries to enforce a judgment that has expired, the FDCPA gives the consumer a claim for actual damages, statutory damages of up to $1,000, and attorney’s fees.
How long does a judgment last? It depends on your state
Every state sets its own rules for how long a judgment can be enforced and how it can be renewed. A few examples:
- California: A money judgment generally can’t be enforced after 10 years unless it is renewed (Code Civ. Proc. § 683.020). Under current law, judgments on personal debt with less than $50,000 in unpaid principal, and on medical debt with less than $200,000, can be renewed only once, for five years (§§ 683.110(c), 683.120(c)).
- Arizona: A creditor has 10 years from entry, or from the last renewal, to enforce a judgment. After that, no execution may issue unless the judgment was renewed by affidavit or by a new lawsuit (A.R.S. § 12-1551).
- Texas: If no writ of execution is issued within 10 years after the judgment, the judgment becomes dormant and can’t be executed unless it is revived (Civ. Prac. & Rem. Code § 34.001).
- Florida: An action on a judgment from a Florida court of record must be brought within 20 years (Fla. Stat. § 95.11(1)).
- Pennsylvania, New Jersey, Maryland and Tennessee have their own enforcement periods and revival or renewal procedures. Some of them are longer, and the details matter. Whether a particular judgment is still enforceable depends on its date, the court that entered it, and what the creditor has filed since.
What to do if a collector comes after you on an old judgment
- Find the judgment date. Look up the case on your court’s online docket or ask the clerk. Write down when the judgment was entered and whether anything was filed later to renew, extend or revive it.
- Read the garnishment papers closely. Check the creditor’s name, any assignment, the claimed balance and the interest. A judgment that has been sold several times is more likely to have gaps or mistakes.
- Act fast. Garnishment notices usually come with short deadlines to claim exemptions or object. Missing them can mean losing money you could have protected.
- Don’t assume you have to pay. An expired or dormant judgment may not be collectible through garnishment at all. Even a valid judgment may carry interest or fees that don’t add up.
- Keep everything. Save the envelopes, letters, writs and pay stubs that show money withheld. FDCPA claims generally must be filed within one year of the violation (15 U.S.C. § 1692k(d)).
- Get advice before you sign anything. A payment plan or new agreement can sometimes create new obligations. Have a lawyer look at it first.
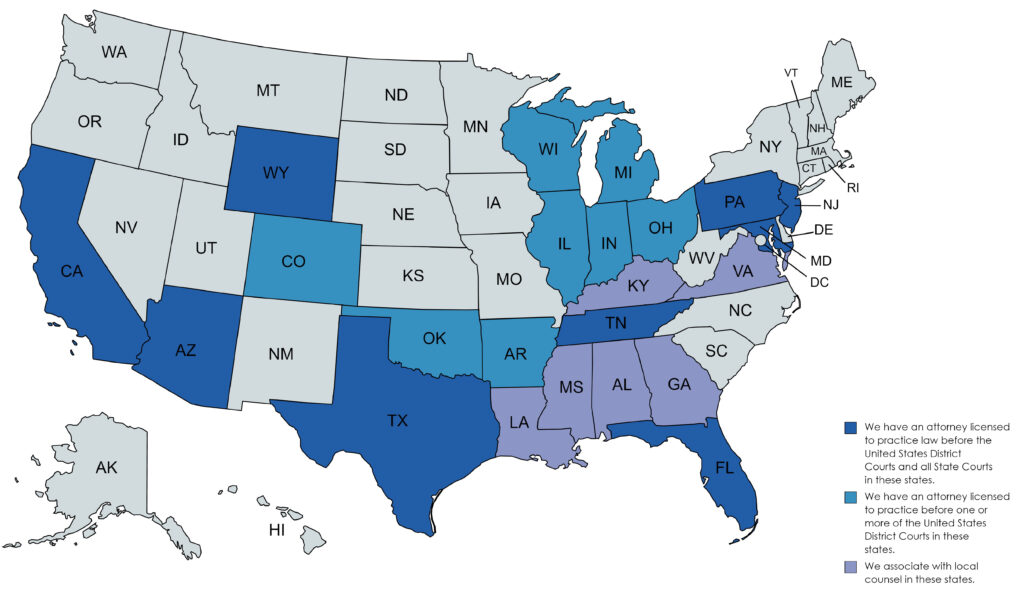
For more background, see our guides to wage garnishment rights and how many days you have to respond to a debt lawsuit in our states.
Ginsburg Law Group defends consumers against collection lawsuits and garnishments, and we hold collectors accountable when they try to collect what the law doesn’t allow. If a collector is garnishing your wages or bank account on an old judgment, contact us for a review.
This article is for general informational purposes only and is not legal advice. Lucianna v. SB&C is a trial-court ruling on liability. Damages haven’t been decided, and the ruling may be appealed. Judgment enforcement and renewal rules vary by state and change over time. Consult a licensed attorney about your specific situation.
Authoritative Sources
- Lucianna v. SB&C, Ltd., No. 2:24-cv-00456-RAJ (W.D. Wash. Sept. 23, 2026), Order on Cross-Motions for Partial Summary Judgment (via CourtListener)
- AccountsRecovery.net: Judge Grants MSJ to Plaintiffs in FDCPA Case Over Expired Judgment (Oct. 5, 2026)
- RCW 6.17.020 (Washington judgment enforcement period)
- 15 U.S.C. § 1692e (Cornell LII)
- 15 U.S.C. § 1692f (Cornell LII)
- 15 U.S.C. § 1692k (Cornell LII)
- Cal. Code Civ. Proc. § 683.020
- Cal. Code Civ. Proc. § 683.110
- A.R.S. § 12-1551
- Tex. Civ. Prac. & Rem. Code ch. 34
- Fla. Stat. § 95.11