
The Consumer Financial Protection Bureau (CFPB) is the federal agency that writes and enforces many of the rules governing debt collectors, credit reporting companies, banks and lenders. For most of the past year, it has been fighting for its survival. On Friday, September 25, 2026, a federal court handed the agency’s supporters a significant win.
In State of New York, et al. v. Vought, et al., No. 6:25-cv-02384-AA, U.S. District Judge Ann Aiken of the District of Oregon granted partial summary judgment to a coalition of 22 states and the District of Columbia. She held that the CFPB’s decision to stop requesting funding from the Federal Reserve was contrary to law and violated the constitutional separation of powers.
How the CFPB is funded, and what went wrong
Unlike most federal agencies, the CFPB isn’t funded through annual appropriations. Under the Dodd-Frank Act (12 U.S.C. § 5497), the Bureau’s director requests the amount “reasonably necessary” to run the agency, and the Federal Reserve transfers it from the Fed’s “combined earnings,” up to a statutory cap.
In November 2025, the Justice Department’s Office of Legal Counsel issued a memo concluding that “combined earnings” means the Fed’s profits. Because the Fed’s interest expenses have exceeded its income in recent years, the memo concluded there was no money the CFPB could lawfully draw. Then-Acting Director Russell Vought took the position that he would not request Federal Reserve funding whenever the Fed had no “profits.” The states sued in December 2025.
What the court decided
- “Combined earnings” means gross revenue. The court declared that the term means the Federal Reserve’s gross revenues, without subtracting expenses. The Fed must transfer to the CFPB the amount the director determines is reasonably necessary.
- The funding cutoff was vacated. The court set aside both the determination that the CFPB can’t request funds when the Fed’s interest expenses exceed its income and the decision not to request funding for fiscal year 2026.
- A separation-of-powers violation. The court found that refusing to request funding Congress had provided was an attempt to take over Congress’s “power of the purse.”
- No new injunction. Because fiscal year 2026 is ending, the court declined to issue an injunction about this year’s funding. Its relief is declaratory: it states what the law requires.
This is not the first ruling of its kind. A federal court in Washington, D.C. rejected the same funding theory in December 2025, and the Northern District of California did the same in March 2026. Both of those cases are on appeal. The government can also appeal this decision, so the fight over the CFPB’s funding isn’t over.
Why this matters to everyday consumers
The CFPB writes and enforces rules under the Fair Debt Collection Practices Act (including Regulation F, which limits how often collectors can call and how they can text and email) and the Fair Credit Reporting Act. It also supervises the largest credit reporting companies and debt collectors. According to the New Jersey Attorney General’s Office, the CFPB has returned more than $21 billion to more than 205 million consumers since it was created.
The Bureau also runs the consumer complaint system. The court specifically noted that federal law requires the CFPB to share complaint information with state agencies, and that states would lose that access if the agency went unfunded. States use those complaints to find bad actors and bring their own enforcement cases.
The state-by-state picture
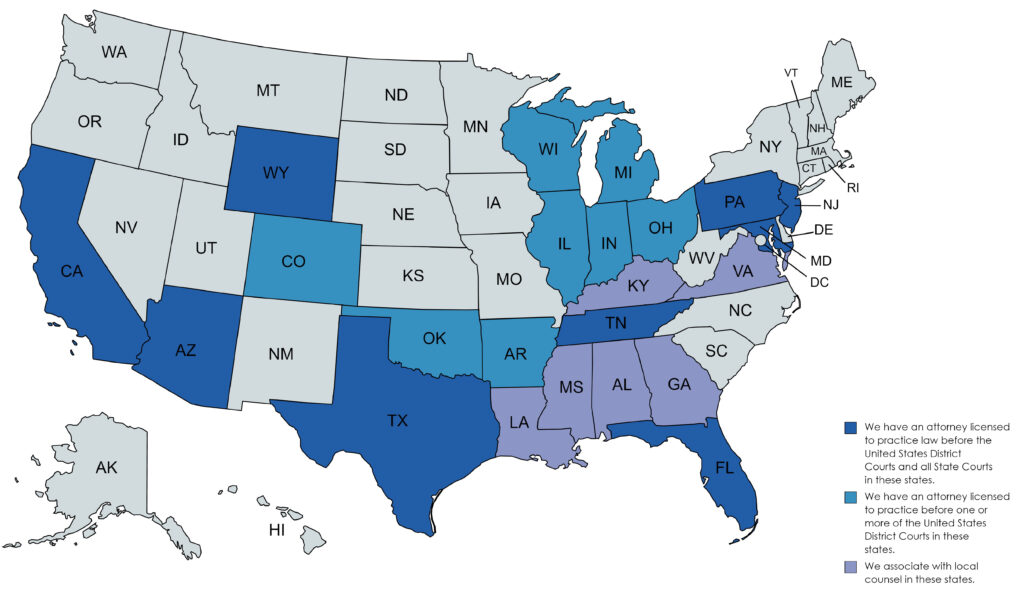
Among the states where Ginsburg Law Group practices, Arizona, California, Maryland and New Jersey are plaintiffs in the case. Pennsylvania, Texas, Tennessee, Florida and Wyoming did not join. The ruling itself concerns how a federal agency is funded, so it applies to the CFPB nationwide, not only in the plaintiff states.
Congress is also weighing the CFPB’s future. On September 16, 2026, the House Financial Services Committee approved H.R. 10184, the Consumer Financial Protection Accountability and Reform Act of 2026. Among other changes, the bill would end the CFPB’s Federal Reserve funding and move the Bureau into the regular congressional appropriations process. The bill is only proposed. It has not passed the House or the Senate.
What this means for you right now
- Your private rights don’t depend on the CFPB. Whatever happens to the agency, the FDCPA, FCRA and TCPA still let consumers sue collectors, credit bureaus and callers who break the law, and they can recover damages and attorney’s fees.
- You can still file a CFPB complaint. If a collector, credit bureau, bank or lender has treated you unfairly, a complaint through the CFPB’s online portal creates a record and requires the company to respond.
- Your state attorney general is another option. State consumer protection offices take complaints and bring their own cases, often using the same CFPB data this lawsuit was meant to protect.
- Don’t wait on Washington. If you’ve been sued over a debt, have an error on your credit report or are getting harassing calls, deadlines are running now. Missing a court deadline can lead to a default judgment, garnishment or a frozen bank account.
Ginsburg Law Group represents consumers against debt collectors, credit reporting agencies and lenders who break the law, and we defend people sued over consumer debts. If you’re facing a collection lawsuit, a credit reporting error or collector harassment, contact us for a review of your situation.
This article is for general informational purposes only and is not legal advice. The court’s September 25, 2026 decision may be appealed, related cases remain on appeal, and H.R. 10184 is proposed legislation that may change or never become law. Consult a licensed attorney about your specific situation.
Authoritative Sources
- Opinion & Order, State of New York v. Vought, No. 6:25-cv-02384-AA (D. Or. Sept. 25, 2026)
- California Attorney General: Attorney General Bonta Celebrates Final Win in CFPB Funding Lawsuit (Sept. 25, 2026)
- WRNJ Radio: Federal Judge Rejects Effort to Defund Consumer Financial Protection Bureau (Sept. 27, 2026)
- Courthouse News Service: Judge Orders Feds to Restore Consumer Watchdog Funding (Sept. 25, 2026)
- House Financial Services Committee: Section-by-Section of H.R. 10184
- 12 U.S.C. § 5497, CFPB Funding (Cornell LII)
- CFPB: Submit a Complaint