
Payday loans, car-title loans and online installment loans can carry annual interest rates of 300% or more. For more than a decade, active-duty servicemembers and their families have been protected from those rates by the Military Lending Act (MLA), which caps most consumer credit at a 36% “military annual percentage rate.” Veterans, retirees and everyone else have no such federal limit.
A new bipartisan bill aims to change that. On September 16, 2026, Rep. Glenn Grothman (R-WI) and Rep. Jesús “Chuy” García (D-IL) introduced H.R. 10439, the Veterans and Consumers Fair Credit Act, which would extend the MLA’s protections to all consumers nationwide. The bill has been referred to the House Committee on Financial Services. A similar Senate proposal, the Predatory Lending Elimination Act (S. 3793), was introduced by Sen. Jack Reed and others in February 2026.
What the bill would do
- A 36% all-in rate cap. Most consumer credit could not exceed a 36% annual percentage rate, calculated the way the Department of Defense calculates the MLA rate. That means many fees and add-on products count toward the cap, which makes it much harder to hide the true cost of a loan in “fees” instead of “interest.”
- Stronger state laws stay in place. The bill sets a federal floor, not a ceiling. States with tougher rules could keep them.
- Some loans are excluded. Under the bill text, residential mortgages, car loans that finance the purchase of the car securing them, and federal credit union loans (which have their own usury limit) would be exempt.
- Real consequences. The MLA’s remedies would apply, including the rule that a loan violating the cap is void. State attorneys general and regulators could bring civil actions, and the Consumer Financial Protection Bureau would write the implementing rules.
- Not immediate. If enacted, the cap would apply to credit extended after the CFPB’s compliance date or 18 months after enactment, whichever comes first. It would not reach back to existing loans.
Why it matters
High-cost loans are designed to be renewed. The sponsors point out that most payday-loan fees come from borrowers who can’t repay the first loan and take out another to cover it. That cycle is exactly where many of the collection lawsuits we defend begin: a small loan turns into a large balance, then a charge-off, then a lawsuit from the lender or a debt buyer.
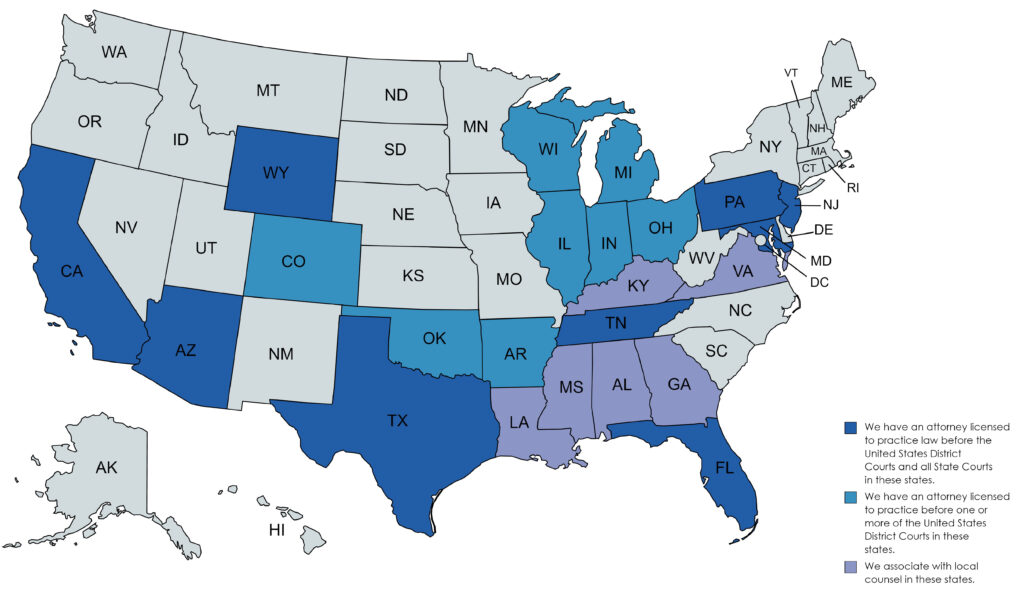
Where you live already makes a big difference. Pennsylvania, New Jersey, Maryland and Arizona don’t permit traditional storefront payday lending. Texas, Tennessee, Florida and California allow payday or similar short-term loans under their own state rules, and in some of those states the effective annual rates can reach triple digits. A national 36% cap would mostly change the rules in states like these.
What this means for you right now
The bill is only proposed. It has not passed either chamber, and most bills never become law. Until something changes, these are the protections that already exist:
- If you’re on active duty (or a covered dependent), the MLA already applies. A loan that violates it, for example by charging more than 36% or requiring mandatory arbitration, is void from the start under federal law.
- If you live in a state that bans payday lending, an out-of-state or online lender charging illegal rates may not be able to enforce the loan against you. Whether the lender was licensed and which state’s law applies can be strong defenses in a collection case.
- If you’re being sued over a high-cost loan, don’t ignore it. Collectors often can’t prove the full amount, the fees they added or their right to collect. Responding on time protects your right to raise every defense.
- If a collector is harassing you over a payday or installment loan, the Fair Debt Collection Practices Act still limits when and how often they can contact you.
Ginsburg Law Group defends consumers sued over payday, installment, title and credit card debts, and we hold lenders and collectors accountable when they break the law. If you’re dealing with a high-interest loan or a collection lawsuit, contact us for a review.
This article is for general informational purposes only and is not legal advice. H.R. 10439 is proposed legislation and may change or never become law. State lending laws vary. Consult a licensed attorney about your specific situation.