
You search for your contact lenses, see a price that beats everyone else, and click through. A few screens later you hit “Continue,” place the order, and only later notice that your card was charged far more than the price you saw. According to a new federal lawsuit, that is exactly what happened to customers of one of the country’s best-known online contact lens sellers.
On October 2, 2026, the Federal Trade Commission, joined by the State of Nevada and the Utah Division of Consumer Protection, sued Lens.com, Inc., an affiliated company called Speed Commerce, LLC, and their owner, Cary Samourkachian, in the U.S. District Court for the District of Nevada (Case No. 2:26-cv-03232). The lawsuit has just been filed. What follows are the government’s allegations, which Lens.com has not yet answered and which the court has not decided.
What the lawsuit alleges
- Low advertised prices. Lens.com allegedly promotes “eye-catching, artificially low prices” in sponsored Google search ads and on its website, and even promises “NO HIDDEN FEES.”
- A mandatory charge hidden “below the fold.” According to the complaint, a required “Taxes & fees” line appears only far down an interim checkout screen. The visible part of the screen encourages shoppers to click “Continue,” so people who follow that prompt never see the charge at all.
- The charge can double the price. The FTC says the fee “routinely doubles” the advertised price. In one example from February 2026, Lens.com advertised a one-year supply for $146.32, and the hidden “Taxes & fees” charge added another $273.44. One customer quoted in the complaint asked, “I do not know how my contacts went from $146 to $245??”
- “Taxes” that aren’t sales taxes. The complaint alleges the “Taxes & fees” charge does not include state sales tax at all. Many states exempt contact lenses from sales tax, yet the label suggests the money is going to the government.
- Subscription problems. Since at least April 2024, Lens.com has sold an “AutoRefill” plan that automatically ships and charges for lenses. The government says the same hidden fee was not clearly disclosed before customers handed over their card information, and that the cancellation method and deadline were buried outside the sign-up process.
The FTC says Lens.com made “hundreds of millions of dollars” through this pricing scheme, and that thousands of customers complained. The Commission voted 2-0 to file the case.
Which laws are involved
The FTC claims violations of Section 5 of the FTC Act (which bans unfair and deceptive practices), the Restore Online Shoppers’ Confidence Act (ROSCA), and the Gramm-Leach-Bliley Act. The GLB claim alleges the company used false price statements to get customers’ card and bank information. ROSCA matters for anyone with an online subscription: a seller using automatic renewal must clearly disclose all material terms before taking your billing information, get your express informed consent before charging you, and give you a simple way to stop the recurring charges.
Nevada sued under its Deceptive Trade Practices Act. Utah sued under its Consumer Sales Practices Act and its Automatic Renewal Contracts Act, which requires a clear notice 30 to 60 days before an automatic renewal stating the renewal date, the total cost and how to cancel. The plaintiffs want a court order stopping the practices, money for consumers, and civil penalties. Utah is also asking the court to declare the AutoRefill renewal terms void.
Why this case matters beyond contact lenses
This is a textbook “drip pricing” case: advertise a low number, then add mandatory charges late in checkout. We covered the practice broadly in our July guide, Hidden Fees Are Finally Under Fire. This case is different because it’s a live enforcement action, and it shows that regulators will go after hidden fees even where no fee-specific rule applies.
That point matters because the FTC’s Rule on Unfair or Deceptive Fees, in effect since May 12, 2025, requires up-front total pricing only for live-event tickets and short-term lodging. Contact lenses aren’t covered. Here the government is relying on the general ban on deception, the online-subscription law and state consumer protection statutes. Those same general laws apply to hidden charges in car deals, apartment leases, gym memberships and online subscriptions of every kind.
The state-by-state picture
- California goes furthest. Under Civil Code § 1770(a)(29), part of the Consumers Legal Remedies Act, it is unlawful to advertise or display a price that leaves out mandatory fees, other than government-imposed taxes and fees and actual shipping costs. California’s new CARS Act brings similar total-price rules to car dealers (see our CARS Act post).
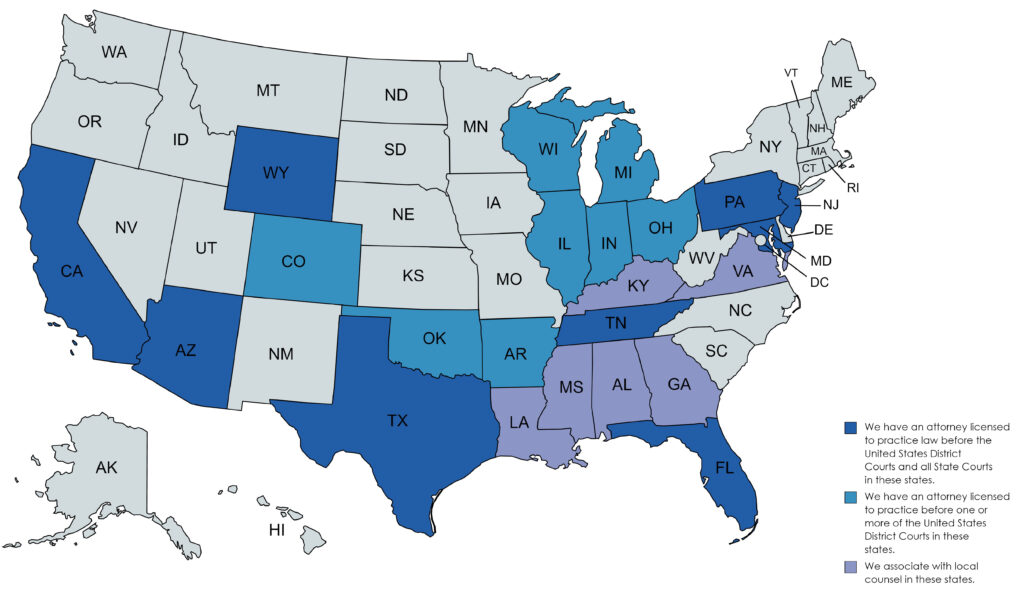
- Pennsylvania, New Jersey, Maryland, Texas, Florida, Tennessee and Arizona have no California-style all-in pricing statute for general retail, but each has a broad consumer protection law, such as Pennsylvania’s UTPCPL, the New Jersey Consumer Fraud Act, the Maryland Consumer Protection Act, the Texas DTPA and Florida’s FDUTPA, that prohibits deceptive pricing and misleading “fee” labels. Several of these laws let consumers sue on their own and recover damages and attorney’s fees.
- Nevada and Utah are the plaintiff states in this case, so their residents may be the first to see any state-level relief.
What this means for you and what to do now
No refund program exists yet. The case has only just been filed, and any money for consumers would come only if the government wins or reaches a settlement. In the meantime:
- Check your past orders. Compare the price you were shown with what your card or bank statement actually shows. Look for any line labeled “taxes & fees,” “service fee,” “processing” or “handling” that you didn’t expect.
- Dispute recent charges. Under the federal Fair Credit Billing Act, you generally have 60 days from the date the statement was sent to dispute a billing error on a credit card in writing. Debit-card and bank-account protections are weaker, so act quickly.
- Review your subscriptions. Find every automatic-renewal plan you’re enrolled in, write down the cancellation deadline, and save the confirmation when you cancel.
- Screenshot before you pay. When you shop online, capture the advertised price and the final order summary. That record is the best evidence if the numbers don’t match.
- Report it. You can file a complaint at ReportFraud.ftc.gov and with your state attorney general.
- Watch for refund scams. The FTC never asks you to pay money to receive a refund. Ignore anyone who calls or texts promising a “Lens.com settlement payment” in exchange for a fee or your account information.
Ginsburg Law Group represents consumers in deceptive-pricing, hidden-fee, dealer-fraud and other consumer protection matters. If you were charged far more than an advertised price, or you can’t get out of an automatic-renewal plan, contact us for a review.
This article is for general informational purposes only and is not legal advice. The claims against Lens.com are allegations in a pending lawsuit; the defendants have not been found liable. Consumer protection laws vary by state. Consult a licensed attorney about your specific situation.
Authoritative Sources
- FTC press release: FTC, States Sue Lens.com for Misrepresenting the Price of Contact Lenses in Search Ads and on Its Website (Oct. 2, 2026)
- Complaint, FTC et al. v. Lens.com, Inc., No. 2:26-cv-03232 (D. Nev. filed Oct. 2, 2026)
- 15 U.S.C. § 8403, Restore Online Shoppers’ Confidence Act (Cornell LII)
- 16 C.F.R. Part 464, Rule on Unfair or Deceptive Fees (eCFR)
- California Civil Code § 1770 (leginfo)
- News 3 Las Vegas: FTC, Utah and Nevada sue Lens.com (Oct. 3, 2026)