
Two years ago, the Federal Trade Commission accused three North Texas car dealerships of sneaking thousands of dollars of unwanted extras into buyers’ contracts. On October 5, 2026, the FTC dropped the case. The agency didn’t find that the dealers did nothing wrong, and it never got a ruling on the merits. It said the fight over its own procedures could drag on for years and that continuing was no longer in the public interest.
If you bought a car in Texas, or anywhere else, and later found charges in your contract you never agreed to, this news does not change your rights. Here’s what happened and what you can still do.
What the FTC alleged
In August 2024, the FTC voted 5-0 to file an administrative complaint against Asbury Automotive Group, three of its Texas dealerships (David McDavid Ford Ft. Worth, David McDavid Honda of Frisco and David McDavid Honda of Irving) and their general manager. According to the FTC’s complaint and press release:
- “Payment packing.” Salespeople allegedly got buyers to agree to a monthly payment that was higher than needed to pay for the car, then “packed” add-on products into the contract to make up the difference.
- Add-ons buyers never agreed to. Consumers reported being charged thousands of dollars for items such as protective coatings, service contracts, and life and disability insurance. Some said the products were never discussed. Others said they declined them and were charged anyway.
- Sign-here screens. Buyers were allegedly asked to sign on electronic devices that showed only the signature spots, not the full documents.
- “It’s mandatory.” Buyers who noticed the charges were allegedly told, falsely, that the add-ons were required.
- Survey results. The FTC said a customer survey showed as many as 75% of buyers at the dealerships reported being charged for add-ons they did not authorize or were falsely told were required.
The original complaint also alleged that Black and Latino buyers paid more for add-ons. The FTC dropped that discrimination count in July 2025. Asbury denied the allegations, and none of them were ever proven or disproven in court.
Why the FTC walked away
Shortly after the complaint was filed, Asbury sued the FTC in federal court in the Northern District of Texas, challenging the constitutionality of the agency’s in-house court system. The FTC case was put on hold while that lawsuit played out. The federal judge denied Asbury’s request for a preliminary injunction and dismissed several of its constitutional claims, but the lawsuit is still pending while Asbury appeals.
In its October 5 order, the Commission said that could mean “years of additional federal court litigation” before anyone reached the actual merits. Weighing its “limited agency resources,” it came to “the difficult conclusion that the public interest requires that this litigation no longer be continued” and dismissed the complaint.
The FTC also said it “remains committed to pursuing price transparency in the appropriate forum, including for automobile dealers.” It pointed to warning letters it sent to 97 auto dealership groups in March 2026 and to an August 2026 settlement with a Connecticut Nissan dealer. Still, the practical effect is that one of the FTC’s highest-profile cases about add-on charges is over with no ruling and no refunds for the buyers it was meant to protect.
Your rights don’t depend on the FTC
The FTC Act does not give individual consumers the right to sue. State consumer protection laws do, and they are often the stronger tool for an individual car buyer.
In Texas, the Deceptive Trade Practices-Consumer Protection Act (DTPA) lets a consumer sue for economic damages caused by false, misleading or deceptive practices. If the jury finds the business acted knowingly, it can award up to three times economic damages plus mental-anguish damages. A consumer who wins is entitled to court costs and reasonable attorney’s fees. Two deadlines matter:
- Notice first. Before suing for damages, you generally must send the business written notice at least 60 days in advance describing your complaint and the amount you’re claiming.
- Two-year limit. DTPA claims generally must be filed within two years of the deceptive act, or within two years of when you discovered it or reasonably should have.
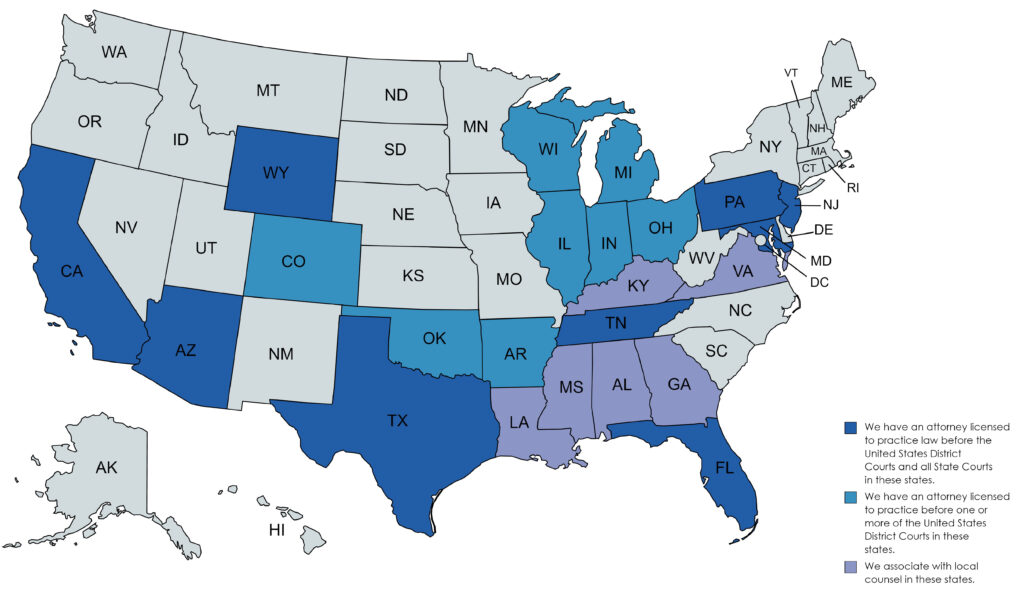
In California, the new CARS Act took effect October 1, 2026, adding total-price and add-on disclosure rules and a 3-day right to cancel many used-car purchases. We covered it in our CARS Act guide. Other states where we practice, including Pennsylvania, New Jersey, Maryland, Tennessee, Arizona and Florida, have their own consumer protection laws that can apply to deceptive dealer add-ons. The details and deadlines differ by state.
What to do if you think your payment was “packed”
- Pull your paperwork. Compare the buyer’s order with the retail installment contract. Look at the itemization of the amount financed for service contracts, GAP, coatings, theft-protection products, or credit life and disability insurance.
- Do the math. If the cash price, taxes and fees you agreed to don’t add up to the amount financed, ask why.
- Ask for complete copies. If you signed on a tablet, request full copies of every document you signed.
- Check cancellation terms. Many add-on products can be canceled, sometimes for a partial refund. Read the product contract and put any cancellation request in writing.
- Write it down. Note what the salesperson told you, especially if you were told a product was “required.”
- Watch the clock. State-law deadlines can be short. Don’t wait to get advice.
For more warning signs, see our guide to dealer fraud red flags after you buy a car.
Ginsburg Law Group represents car buyers in dealer fraud, add-on and lemon law cases. If you were charged for products you didn’t agree to or were told they were mandatory, contact us for a review of your contract.
This article is for general informational purposes only and is not legal advice. The FTC’s allegations against Asbury were never proven, and the company denied them. The case was dismissed without a ruling on the merits. Consumer protection laws and deadlines vary by state. Consult a licensed attorney about your specific situation.
Authoritative Sources
- FTC Order Returning Matter to Adjudication and Dismissing Complaint, In re Asbury Automotive Group, Docket No. 9436 (Oct. 5, 2026)
- FTC case page: Asbury Automotive Group, Inc., et al., In the Matter of
- FTC press release: FTC Takes Action Against Auto Dealer Group Asbury Automotive (Aug. 16, 2024)
- FTC press release: FTC Warns 97 Auto Dealership Groups About Deceptive Pricing (Mar. 13, 2026)
- Texas Business & Commerce Code ch. 17 (DTPA, incl. §§ 17.50, 17.505, 17.565)
- Auto Remarketing: FTC dismisses ‘payment packing’ complaint against Asbury (Oct. 7, 2026)