
By Ginsburg Law Group, P.C. | September 24, 2026
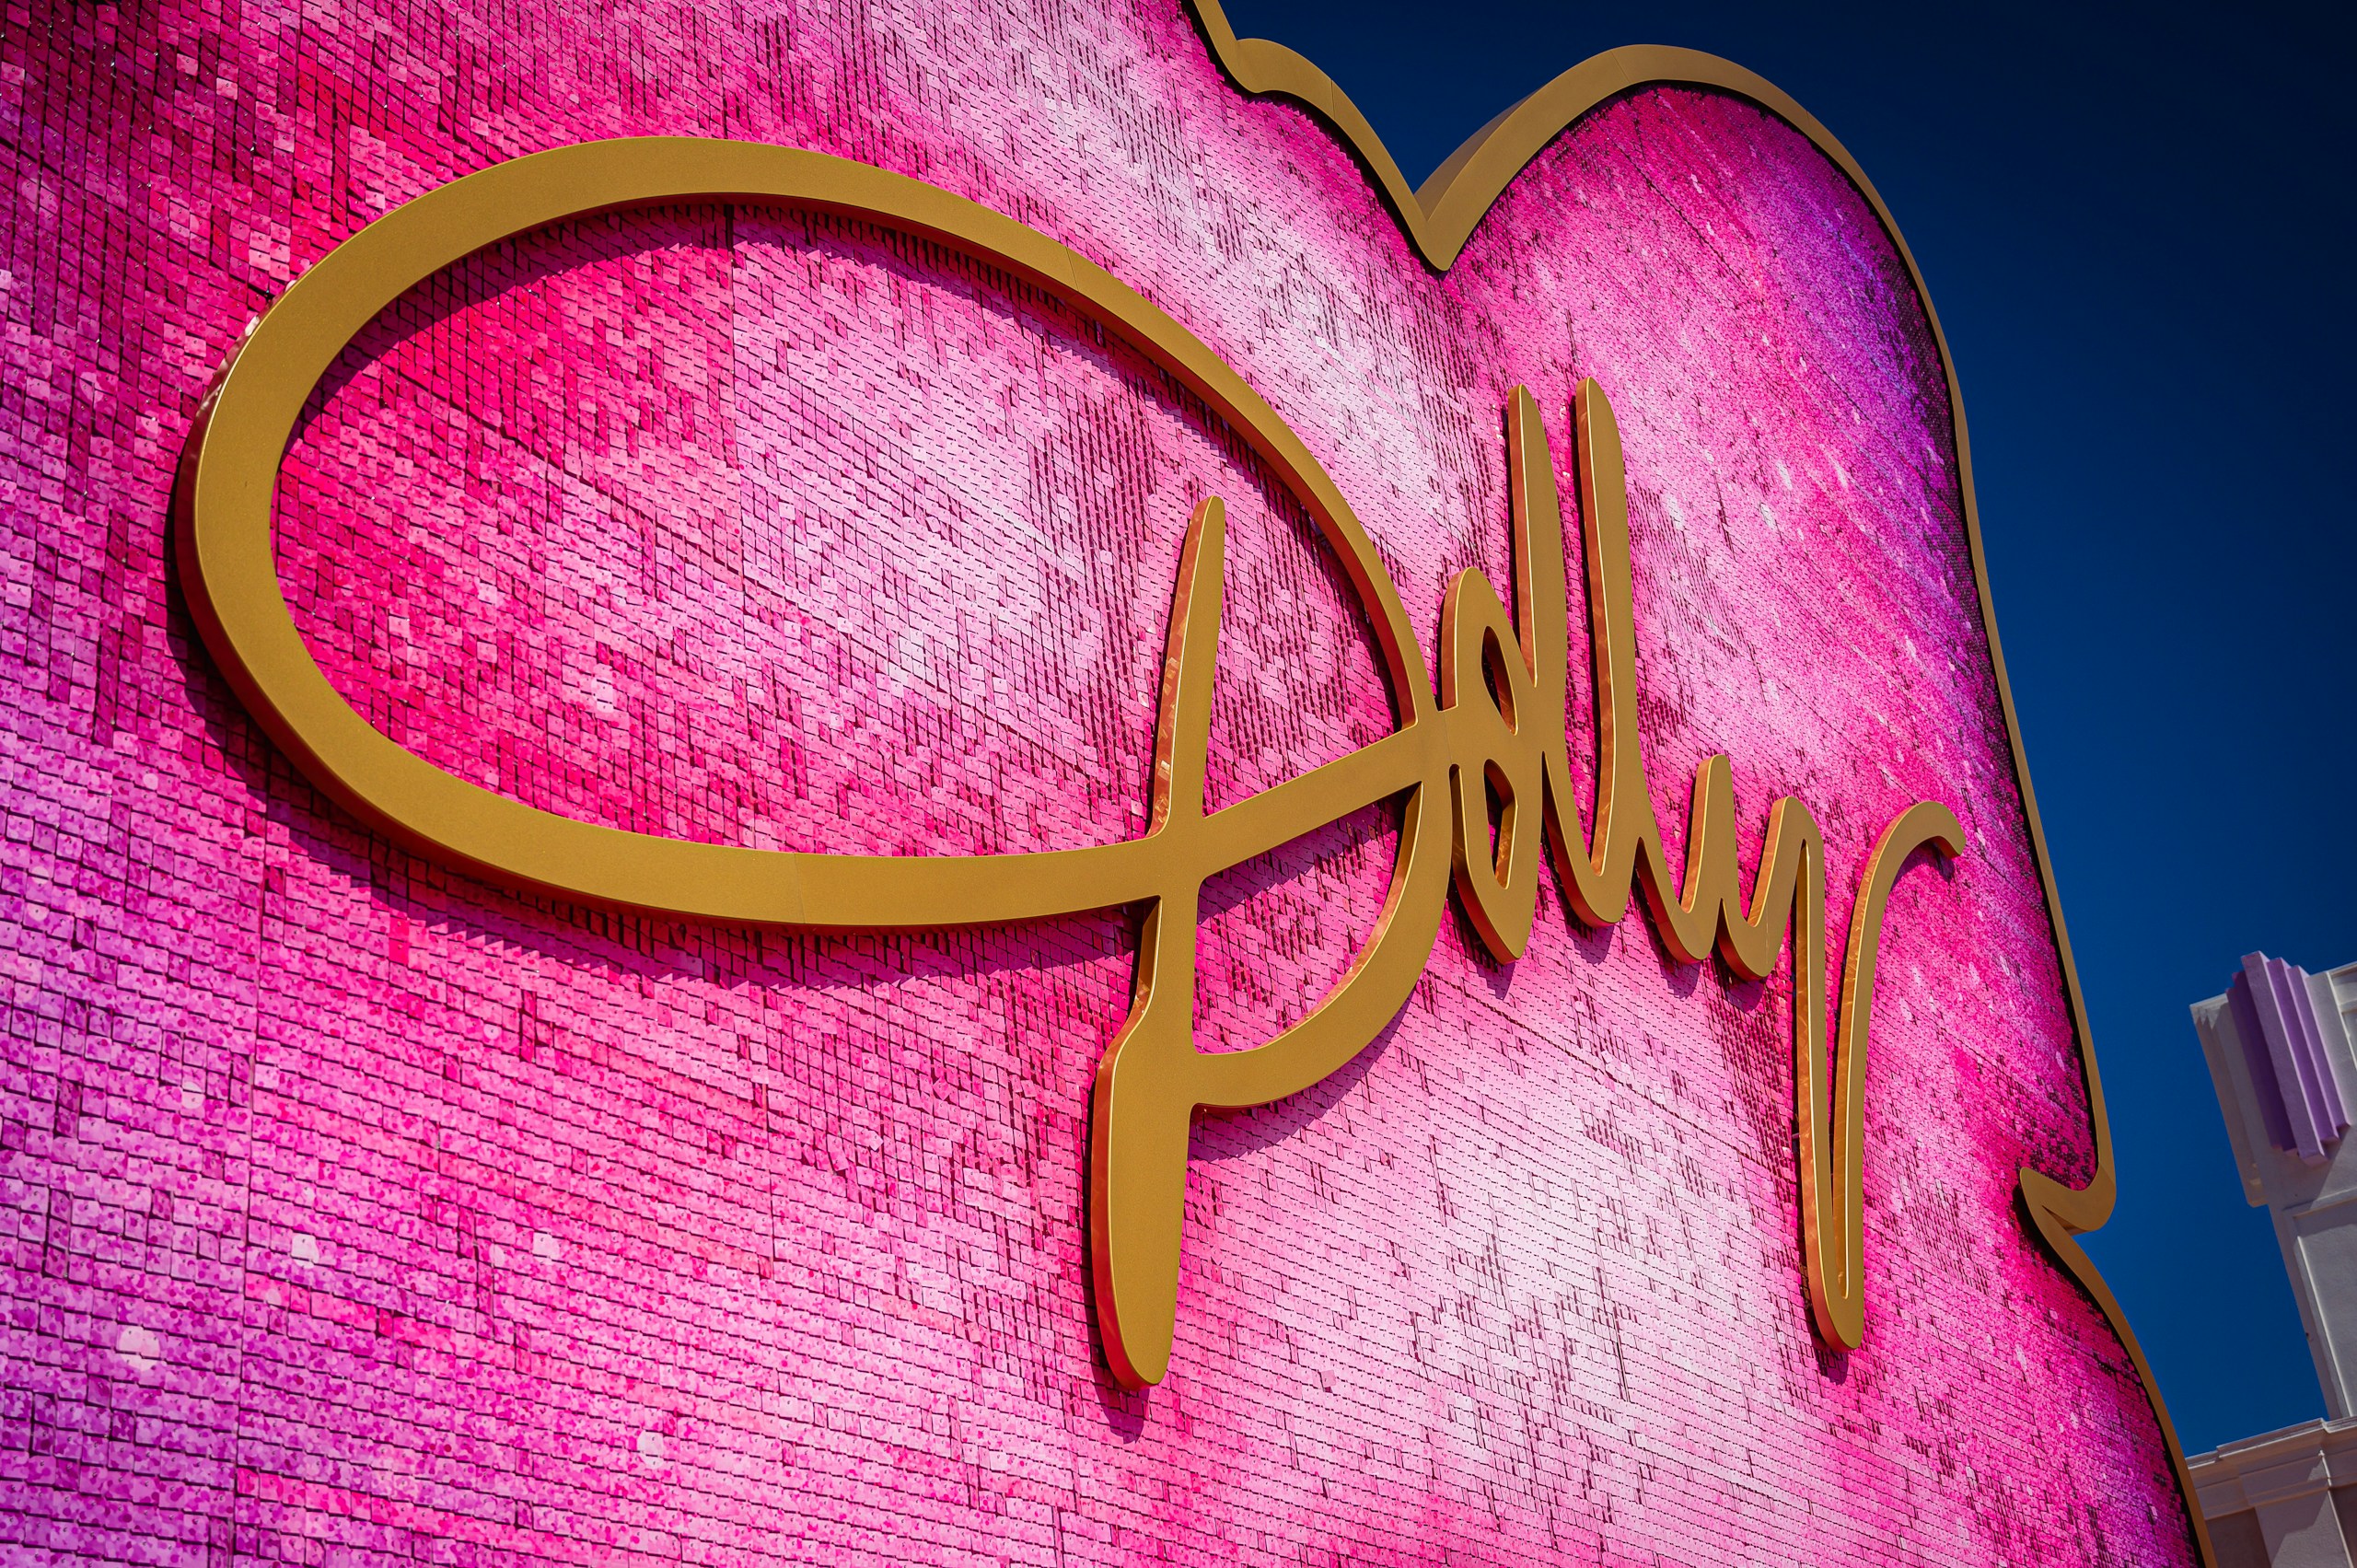
Dolly Parton spent a lifetime building far more than a music career. Her songs, businesses, charitable work, property, and public image form a legacy that will continue long after her death. Managing that legacy requires people to make decisions about contracts, employees, security, intellectual property, and family interests—often while they are grieving.
Recent events have shown how difficult that transition can become. In September 2026, a dispute arose involving Parton’s nephew, Bryan Seaver, whose company had provided security for her properties. After that arrangement ended, a company involved in managing Parton’s business interests filed a court action alleging threats and interference. On September 23, a Tennessee judge granted a temporary restraining order. The allegations remain subject to further court proceedings. The Associated Press reported on the order and the parties’ claims.
There is an important limit to the lesson we can draw: the public reporting does not establish that Parton’s will or trust was poorly drafted, that anyone has challenged their validity, or that different planning would have prevented this dispute. The reported conflict involves a family member’s professional role and the management of continuing business interests. Those issues are related to estate planning, but they are not the same as a fight over who inherits.
That distinction makes this a useful moment for families to ask a broader question: Does your plan explain not only who receives what, but also who will make decisions, who will keep essential work going, and how the transition will happen?
A beneficiary, an employee, and a decision maker have different roles
One person can occupy several places in your life. A daughter might be a beneficiary of your trust and the manager of your company. A nephew might work at your business and expect to inherit property. A longtime friend might hold your power of attorney and serve on a nonprofit board you founded.
Those relationships can feel inseparable while you are alive. Legally and practically, they are different.
A beneficiary may have a right to receive property or information under a will or trust. An employee or contractor has rights and duties arising from an employment or business arrangement. An executor or trustee has authority and obligations under estate documents and applicable law. A business manager may have authority under corporate documents or a contract. Holding one role does not automatically confer the others.
This is why a conversation about “taking care of” a relative can be too vague. Does that mean a financial gift? Continued employment? Ownership in a company? A say in how the company operates? A role in managing the estate? Each possibility calls for a different decision and, often, a different document.
Practical tip: Make a list of relatives and close associates who have more than one connection to your property or business. Beside each name, write down the roles you intend them to have during your life, during incapacity, and after your death. Then ask your estate planning attorney whether the documents actually support those choices.
Plan for the business that must operate the next morning
A will can say who inherits a business interest. It may say little about who is authorized to open the office, sign payroll, speak to a landlord, manage a website, or answer a customer’s call the morning after the owner dies.
For a family business, professional practice, rental portfolio, or creative enterprise, the first few weeks matter. Employees need direction. Bills must be paid. Insurance may require prompt notice. Contracts may contain deadlines or provisions triggered by death or a change in control. Someone may need access to records without gaining unrestricted access to personal accounts.
The American College of Trust and Estate Counsel advises business owners to address succession as part of estate planning. A workable plan should identify who can act immediately, who will manage the business over the longer term, and whether the goal is to continue, transfer, or sell it.
Practical tip: Prepare a short business continuity guide for the people who will take charge. Include key contacts, recurring obligations, insurance information, the location of governing documents, and instructions for accessing essential systems. Keep credentials secure; the guide can explain how authorized people obtain access without placing passwords in a will or another document that may become public.
Address family employment and contracts directly
When a relative works in a business or provides services to it, assumptions about the future can grow over many years. The owner may think, “They have a job as long as it makes sense for the business.” The relative may believe, “I will always have this role because we are family.” Neither belief necessarily appears in an enforceable agreement.
The death of the owner can bring those unspoken expectations into sharp focus. New managers may need to review staffing, costs, access to property, and contracts. A relative may experience a business decision as a personal rejection, particularly if it happens during grief.
Estate planning cannot guarantee that every relative will agree with future management decisions. It can, however, prompt the owner to decide what they actually want. Should a relative have a continuing role? For how long? On what terms? Who evaluates their performance? What happens if the business is sold or the working relationship becomes untenable?
Practical tip: Have an attorney review significant family employment arrangements and service contracts alongside the estate plan. If your intention is to give someone a financial benefit regardless of whether they continue working, consider expressing that benefit separately. An inheritance and a job need not depend on each other.
Choose fiduciaries for the work they will have to do
Naming an executor or trustee is sometimes treated as an honor. It is also a job. The person may need to collect assets, protect property, keep records, pay expenses, communicate with beneficiaries, make judgment calls, and work with attorneys, accountants, and business advisers.
The oldest child is not automatically the best choice. Nor is the person who lives closest, knows the most about the family, or insists that they should be in charge. The right choice depends on the assets and the people involved.
Ask whether the candidate has the time, judgment, organization, and temperament for the role. Can they make decisions that others may dislike? Will they keep careful records? Do they understand when to seek professional help? Could their own financial interests create tension with their duties?
A professional or corporate fiduciary may be useful in some situations, especially where assets are complex or family relationships are strained. That choice comes with fees and should be considered in light of the estate’s size and needs. ACTEC offers guidance on choosing an executor or trustee.
Practical tip: Ask your proposed fiduciary whether they are willing to serve, and name successors. Review those choices periodically. The person who was ideal ten years ago may no longer be available or well suited to the job.
Give decision makers clear authority—and clear limits
A trust or business succession plan should do more than identify a person by name. It should consider the decisions that person may need to make.
Can the trustee retain a family business or must it be sold? Who can hire professionals? Who can manage intellectual property, licensing, or a public-facing brand? Can a manager replace a contractor who happens to be a beneficiary? What approvals are required for major transactions? If two people share authority and disagree, how is the deadlock resolved?
The answers depend on the type of asset, the governing documents, and state law. They should be tailored with counsel rather than copied from a generic form.
Clear authority does not mean unchecked authority. Trustees and other fiduciaries have legal duties, and beneficiaries may have rights to information and remedies under applicable law. The aim is to make the intended chain of command understandable while preserving appropriate accountability.
Practical tip: Ask your attorney to walk through three realistic scenarios: an urgent expense, a dispute with a family member who works for the business, and an offer to sell a major asset. If the plan gives no clear answer about who decides, what information they need, and whom they must consult, it may need more work.
Coordinate the estate plan with the assets themselves
A beautifully written trust cannot manage property it never receives or otherwise controls. A will cannot override every beneficiary designation or every provision of a business agreement. A company operating agreement may restrict transfers or determine who can manage an ownership interest after an owner’s death.
This is where many otherwise careful plans run into trouble. The estate documents say one thing; account designations, deeds, contracts, or company records point elsewhere. The people left behind then have to determine which rules govern which assets.
Review how each significant asset is owned and how it will transfer. That includes real estate, bank and investment accounts, retirement accounts, life insurance, business interests, valuable collections, and digital assets. For a creator or business owner, it may also include trademarks, copyrights, royalties, domains, and licensing agreements.
Practical tip: Keep an asset inventory and review it with your attorney after major purchases, sales, marriages, divorces, deaths, or changes in the business. An inventory need not contain sensitive account credentials to be useful. Its first purpose is to make sure that important property is identified and that the documents work together.
Talk about expectations while you can
Documents matter, but families also carry stories. “Dad always said I would run the company.” “Mom promised me the house.” “I gave up other opportunities to help build this business.” These statements may reflect sincere memories, even when the written plan provides something different.
An owner is entitled to make choices about property and management. Still, a surprise can intensify a disagreement. Where appropriate, a careful conversation during life can help family members understand that receiving an inheritance, working in a business, and controlling that business are separate questions.
This does not mean everyone must agree, or that you need to share private financial details with every relative. Some conversations require particular care where relationships are abusive, coercive, or unsafe. It means considering whether a limited, deliberate explanation would make the transition easier.
Practical tip: Tell the people you appoint that they have been chosen and explain the broad responsibilities. If a relative is likely to assume a role you do not intend them to have, discuss with counsel whether and how to address that expectation. The conversation and the documents should tell a consistent story.
Build a plan for incapacity, not only death
A serious illness can create the same operational questions before anyone dies. Who can pay bills, manage the business, access records, and work with advisers if you cannot act? A successor trustee, financial power of attorney, and business continuity documents may each have a part to play. They do not necessarily grant identical powers over identical property.
A person you trust with household finances may not be the best person to run a company. A business partner may be equipped to handle operations but should not make personal health decisions. Planning lets you assign those responsibilities deliberately.
Practical tip: Test your plan against a six-month absence. If you became unable to work tomorrow, who would have legal authority to manage each account, property, and business interest? Who would know where to find the documents? Identify any gaps before an emergency makes them urgent.
Review the plan when the people or business change
An estate plan is a set of instructions for a future situation you cannot fully predict. Children grow up. Trusted advisers retire. A family member joins—or leaves—a business. A spouse dies. Assets move across state lines. A once-small project becomes a valuable company.
Those changes may affect more than the distribution of property. They may change who is capable of serving as trustee, what skills the business needs, whether an old agreement still fits, and how much information your successors will need.
Practical tip: Set a regular time to review the plan, and revisit it promptly after a major life or business change. Check the names of decision makers, the ownership of assets, beneficiary designations, and the practical instructions for the first days of a transition.
The real goal is a workable transition
The public dispute involving Dolly Parton’s legacy is still developing. It would be unfair to claim that her estate plan caused it or that any document could have guaranteed a different result. People can disagree—and behave unpredictably—even when a plan is careful.
What families can take from the news is a reason to look beyond the familiar question of “Who gets my property?” A complete conversation also asks: Who takes charge? What authority will they have? What happens to a family member’s job or contract? Who keeps a business running? What records will the decision makers need? How will beneficiaries understand what is happening?
For most families, the assets will look nothing like Dolly Parton’s. The underlying questions can be remarkably similar. A home, a small business, a family rental property, or a relative’s longstanding role can carry financial and emotional weight far beyond its dollar value.
At Ginsburg Law Group, P.C., we help clients examine both the legal documents and the practical steps their loved ones will face. Thoughtful planning cannot promise a conflict-free future. It can leave clearer instructions, better prepared decision makers, and fewer unanswered questions at a difficult time.
This article provides general educational information, not legal advice for a particular person or estate. Estate, trust, employment, and business laws vary by state, and the appropriate plan depends on the facts.