
Most people who want to shrink a taxable estate run into the same problem. To get assets out of your estate, you have to give them away, and once they’re gone, you can’t use them. A Spousal Lifetime Access Trust (SLAT) is one of the most popular ways married couples handle that problem. One spouse makes a gift to an irrevocable trust for the benefit of the other spouse, and often children or grandchildren too. The assets, and all their future growth, are removed from the giving spouse’s estate, but the family keeps indirect access through the beneficiary spouse.
SLATs are powerful, but the IRS rules are technical. A SLAT that is drafted or funded carelessly can end up back in someone’s taxable estate, or leave one spouse paying income tax on money the other spouse receives after a divorce. Here’s what married couples should understand before they sign.
How a SLAT works
- The donor spouse (the “grantor”) transfers assets to an irrevocable trust. The gift uses part of the donor’s lifetime gift and estate tax exemption.
- The beneficiary spouse can receive distributions during his or her lifetime, usually for health, education, maintenance and support, or at a trustee’s discretion.
- Children or other descendants are typically the remainder beneficiaries after the beneficiary spouse dies, often in continuing trusts.
- A trustee manages the trust. The beneficiary spouse can sometimes serve, but only with limits (more on that below).
Because the donor spouse isn’t a beneficiary, the trust assets are generally not included in the donor’s estate at death. If it’s drafted correctly, they’re not included in the beneficiary spouse’s estate either.
Why SLATs still matter after the 2025 tax law
For years, SLATs were driven by fear of a scheduled drop in the federal exemption at the end of 2025. That cliff is gone. The 2025 federal tax law (Public Law 119-21) set the basic exclusion amount at $15,000,000 per person for 2026, indexed for inflation starting in 2027, with no scheduled sunset. The generation-skipping transfer (GST) tax exemption is also $15,000,000 for 2026, and the annual gift tax exclusion stays at $19,000 per recipient for 2026. The IRS hasn’t yet announced the 2027 inflation-adjusted figures.
So why would a couple still use a SLAT? Because the reasons were never just about the cliff:
- Freezing growth. Appreciation after the gift happens outside your estate. A $5 million gift of a growing business interest or investment portfolio can be worth far more by the time you die, and none of that growth uses more exemption.
- “Permanent” means until Congress changes it. Tax law changes with elections. Using exemption now locks it in. IRS anti-clawback regulations protect gifts made under a higher exemption if the exemption is later reduced.
- State estate and inheritance taxes. Maryland has an estate tax with a $5 million exemption and a separate inheritance tax. Pennsylvania and New Jersey have inheritance taxes. Lifetime gifts can reduce state-level exposure, although each state has its own rules (Pennsylvania, for example, can tax gifts made within one year of death).
- Creditor protection. A properly drafted irrevocable trust with spendthrift provisions can protect assets from future creditors and lawsuits.
- Income tax “burn.” Most SLATs are grantor trusts, so the donor spouse pays the income tax on trust earnings. That lets the trust grow tax-free, and each tax payment is effectively an additional tax-free gift.
IRS consideration #1: the gift is real, and you have to report it
Funding a SLAT is a completed gift. It isn’t covered by the unlimited marital deduction, because the goal is to use the donor’s exemption rather than defer tax until the second death. That means:
- File Form 709. The donor spouse must file a federal gift tax return (Form 709) for the year of the gift, generally due April 15 of the following year. No tax is usually owed, because the gift is applied against the lifetime exemption, but the return is still required.
- Disclose adequately. For hard-to-value assets such as closely held business interests or real estate, attach a qualified appraisal and meet the IRS adequate-disclosure rules. Adequate disclosure starts the three-year period for the IRS to challenge the value. Without it, the IRS can question the value years later.
- Gift splitting usually isn’t available. Normally, spouses can elect to treat a gift as made half by each spouse. The regulations only allow that when the consenting spouse’s own interest in the trust is ascertainable and severable from everyone else’s. In most SLATs it isn’t, so couples should assume the gift counts entirely against the donor spouse’s exemption.
- Decide on GST exemption. If grandchildren may eventually benefit, the Form 709 is where you allocate GST exemption, or elect in or out of the automatic allocation rules. Getting this right on the first return is much easier than fixing it later.
IRS consideration #2: grantor trust status and who pays the income tax
Under Internal Revenue Code § 677, a trust is a “grantor trust” for income tax purposes if its income may be distributed to, or accumulated for, the grantor’s spouse without the consent of an adverse party. Since a SLAT exists to benefit the spouse, it is almost always a grantor trust. The donor spouse reports all of the trust’s income on his or her own return.
That’s usually a feature, not a bug, but couples should plan for it:
- Tax reimbursement clauses. Under Revenue Ruling 2004-64, a trustee’s discretionary power (if permitted by the trust and state law) to reimburse the grantor for the income tax doesn’t cause estate inclusion, as long as there’s no understanding or requirement that it be paid.
- Swap powers. Many SLATs give the grantor a power to substitute assets of equal value. That can keep grantor trust status and lets the grantor swap low-basis assets back into the estate before death to get a step-up in basis.
IRS consideration #3: don’t let the assets come back into an estate
The whole point of a SLAT is that the assets are outside both spouses’ estates. Several Code sections can undo that:
- Retained interests (§§ 2036 and 2038). The donor spouse can’t be a beneficiary, can’t keep control over who benefits or when, and shouldn’t use trust assets in a way that indirectly benefits himself or herself. Distributions shouldn’t be used to pay obligations the donor already has, such as the legal duty to support a spouse.
- The beneficiary spouse as trustee (§ 2041). If the beneficiary spouse is a trustee, distributions to himself or herself should be limited to an “ascertainable standard,” meaning health, education, maintenance and support. Broader discretion should belong to an independent trustee. Otherwise, the beneficiary spouse may hold a general power of appointment, and the assets can be taxed in his or her estate.
- Life insurance (§ 2035). If an existing life insurance policy is transferred to the SLAT and the donor dies within three years, the proceeds are pulled back into the donor’s estate. Having the trust buy a new policy avoids that.
IRS consideration #4: the reciprocal trust doctrine
Many couples ask, “Can we each create a SLAT for the other?” You can, but this is where many plans get into trouble. Under the reciprocal trust doctrine, recognized by the U.S. Supreme Court in United States v. Estate of Grace, 395 U.S. 316 (1969), if two trusts are interrelated and leave each spouse in roughly the same economic position as if each had created a trust for himself or herself, the IRS can “uncross” them. Each spouse is then treated as the grantor of the trust benefiting him or her, and both trusts are included in the estates.
If both spouses want SLATs, the trusts should be meaningfully different. Common ways to do that include:
- Creating the trusts at different times, ideally months apart, and funding them with different assets and amounts
- Giving each beneficiary spouse different rights, such as a power of appointment in one trust but not the other, or different distribution standards
- Using different trustees and different remainder beneficiaries or terms
IRS consideration #5: where the money comes from
The assets used to fund a SLAT must belong to the donor spouse. If the beneficiary spouse effectively supplied the money, for example through a transfer to the donor right before the gift, the IRS can argue the beneficiary spouse is really a grantor of his or her own trust. That can pull assets into the beneficiary spouse’s estate under § 2036.
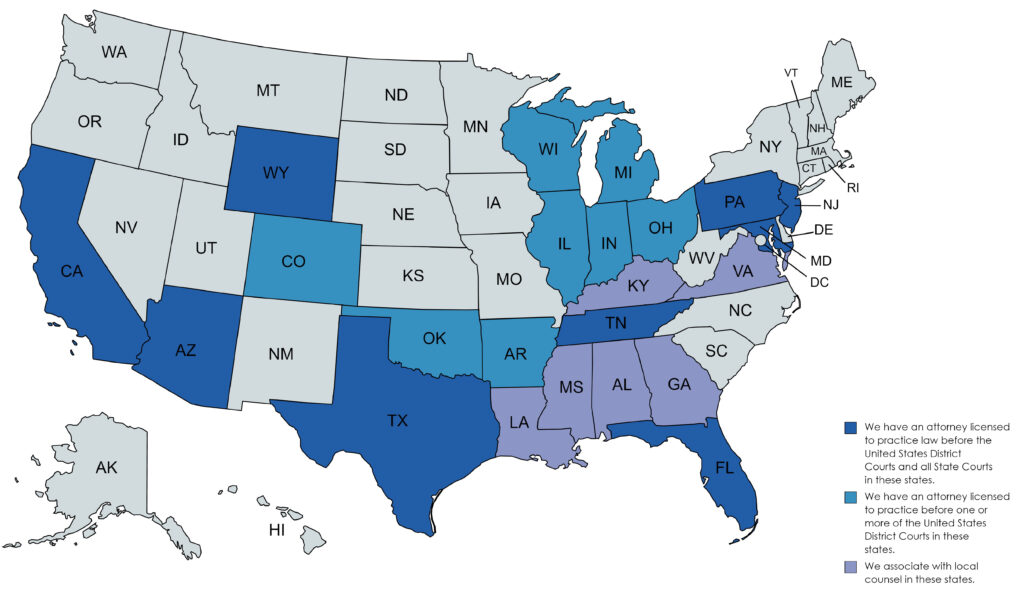
This matters especially in community property states, including California, Arizona and Texas. Community property belongs half to each spouse. If community property goes into a SLAT, the beneficiary spouse may be treated as having contributed half. Couples in those states usually need a written agreement converting the assets to the donor’s separate property (in California, a transmutation that meets Family Code § 852) well before the SLAT is funded. That step has its own consequences, including the possible loss of the full basis step-up that community property gets at the first death.
IRS consideration #6: divorce
A SLAT is irrevocable. Divorce doesn’t end it. Under § 672(e), the donor is treated as holding the powers and interests of anyone who was his or her spouse when the trust was created. That means the donor spouse can keep paying the income tax on trust income that’s distributed to an ex-spouse. Before 2019, § 682 could shift that tax to the ex-spouse, but the 2017 tax law repealed § 682 for divorce or separation instruments executed after 2018.
Couples can plan for this. For example, the trust can define “spouse” as the person the donor is married to at any given time (a “floating spouse” clause), give an independent party the power to turn off grantor trust status, and coordinate the SLAT with a prenuptial or postnuptial agreement.
IRS consideration #7: no step-up in basis
Assets that are outside your estate don’t get a stepped-up income tax basis when you die. The beneficiaries take the donor’s original basis, under § 1015. For a highly appreciated asset, the capital gains tax the children could eventually pay may outweigh the estate tax saved, especially for families whose estates are below the $15 million federal exemption. That’s why SLATs are often funded with cash or high-basis, high-growth assets, and why a swap power is so valuable.
What happens if the beneficiary spouse dies first?
This is the biggest practical risk. The donor spouse’s “access” to the SLAT runs through the beneficiary spouse. If the beneficiary spouse dies first, the trust typically passes to the children, and the donor loses that indirect safety net. Couples should make sure the donor keeps enough assets outside the trust to live comfortably. They can also consider life insurance on the beneficiary spouse, or giving the beneficiary spouse a limited power of appointment that can keep assets available for a new spouse.
Don’t forget portability
SLATs and portability work together. When the first spouse dies, the estate can elect to transfer the unused exemption, called the deceased spousal unused exclusion or DSUE amount, to the surviving spouse by filing a timely Form 706. That election is available even when no estate tax is owed. Under Revenue Procedure 2022-32, many estates that weren’t otherwise required to file can still make the election up to five years after death. Couples who use a SLAT to spend one spouse’s exemption should make sure the other spouse’s unused exemption isn’t wasted.
Is a SLAT right for you?
A SLAT is usually worth a serious look if:
- Your combined estate is large enough that federal estate tax is a real possibility, now or in the future, or you live in or own property in a state with its own estate or inheritance tax
- You have assets you expect to grow significantly
- Your marriage is stable, and you’re comfortable with your spouse controlling access to the gifted assets
- You can afford to give the assets away and still keep enough in your own name
It may not be the right tool if your estate is comfortably below the exemption and the main concern is income tax basis, or if either spouse is uncomfortable with the trust being irrevocable.
Key takeaways
- A SLAT moves assets and their growth out of the donor’s estate while the beneficiary spouse can still benefit.
- The federal exemption is $15 million per person for 2026, but SLATs remain useful for growth, state taxes, asset protection and protection against future law changes.
- File Form 709, disclose values properly and plan your GST allocation. Gift splitting usually isn’t available.
- Avoid reciprocal trusts, be careful about where the funding comes from (especially with community property) and limit a spouse-trustee to an ascertainable standard.
- Plan ahead for divorce, the death of the beneficiary spouse and the loss of basis step-up.
Related reading: California Gifting Trusts, Credit Shelter Trust vs. Portability, Meet the IDGT and Prenups, Postnups and Estate Planning.
Ginsburg Law Group helps married couples design and fund SLATs and coordinate them with the rest of their estate plan. To find out whether a SLAT makes sense for your family, contact us or email info@ginsburglawgroup.com.
This article is for general informational purposes only and is not legal or tax advice. Tax laws and IRS guidance change, and the right structure depends on your assets, your state and your family. Consult a licensed attorney and a qualified tax advisor about your situation.
Authoritative Sources
- IRS: What’s New, Estate and Gift Tax
- IRS Revenue Procedure 2025-32 (2026 inflation adjustments)
- IRS Instructions for Form 709
- 26 U.S.C. § 677 (income for benefit of grantor or spouse)
- 26 U.S.C. § 672 (spouse treated as grantor)
- 26 U.S.C. § 2036 (retained life estate)
- 26 U.S.C. § 2041 (powers of appointment)
- 26 U.S.C. § 2513 (gift splitting)
- United States v. Estate of Grace, 395 U.S. 316 (1969)
- Revenue Ruling 2004-64, Internal Revenue Bulletin 2004-27
- IRS Revenue Procedure 2022-32 (late portability elections)
- Pennsylvania Department of Revenue: Inheritance Tax